
From Tenant to Owner: How Dubai’s First-Time Home Buyer Programme Works
Paying rent every month does not automatically mean buying a home is out of reach. For eligible UAE residents, Dubai’s First-Time Home Buyer Programme offers a more structured route into ownership, with access to selected property launches, developer incentives and mortgage offers from participating banks.
Launched by the Dubai Land Department (DLD) and Dubai Department of Economy and Tourism in July 2025, the initiative is open to Emiratis and expatriates. However, it is not a government-funded deposit or a guarantee of mortgage approval. Buyers still need to qualify financially, compare the available offers, and account for the costs of purchasing a property.
Could You Qualify? Start With These Four Conditions
The programme has a relatively broad eligibility framework. According to DLD, applicants must:
- Be at least 18 years old.
- Be a UAE resident, regardless of nationality.
- Not currently own a freehold residential property in Dubai.
- Be seeking to purchase a property valued below AED 5 million.
The ownership condition is specific to Dubai. DLD confirms that someone who owns property in another emirate, or owns property in a non-freehold location, can still qualify as long as they do not currently own a freehold residential property in Dubai.
This makes the initiative relevant to expatriates who have rented in Dubai for years but have not purchased a home in the emirate.
There is no additional salary threshold set by the programme itself. Mortgage eligibility, however, remains subject to the participating bank’s income, affordability, and credit assessment.
What Do First-Time Buyers Actually Receive?
The programme brings together developers, banks and DLD to offer benefits at different stages of the purchase. The exact offer depends on the partner and property.
Priority access to selected launches
Registered buyers can receive early access to new developments and selected existing inventory from participating developers. This can be useful when demand for a particular project is high, although priority access does not guarantee a preferred unit.
Developer pricing and payment terms
Participating developers may offer preferential prices on selected properties, along with flexible payment plans for eligible off-plan units. These offers are not necessarily available across every project or apartment.
Mortgage offers through partner banks.
Buyers can approach participating banks for tailored home financing, which may include preferential interest rates, reduced fees, or faster processing. Approval and final terms remain the bank’s decision.
More flexibility with registration fees
DLD lists payment plans for registration fees through eligible credit cards, including interest-free installments where offered. This changes how eligible fees can be paid, not whether they are owed.
How to Register and Use the Programme
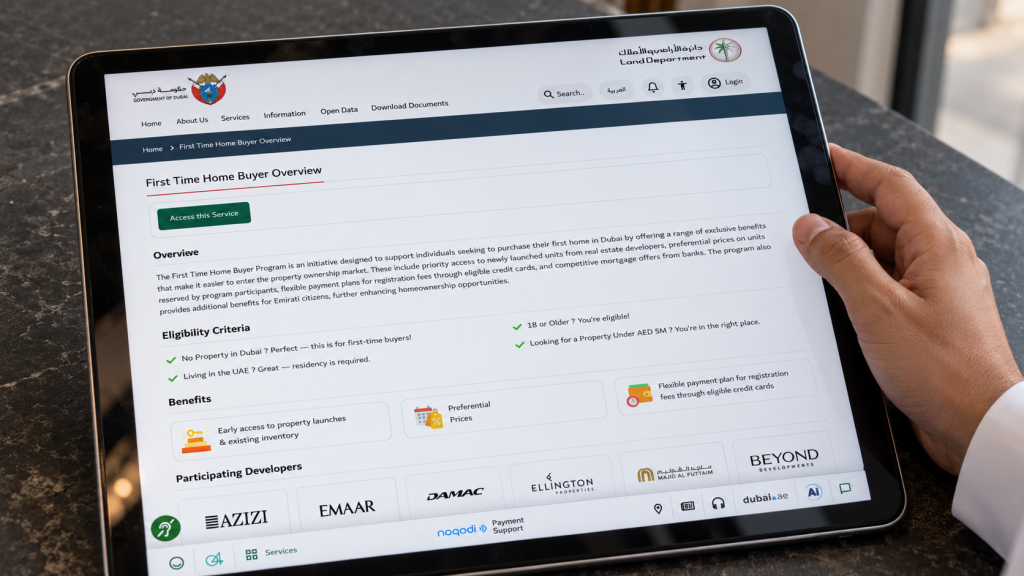
Registration takes place through the DLD website or the Dubai REST app. The process is straightforward, but it is worth completing before approaching a developer or negotiating a purchase.
- Submit your registration: Access the First-Time Home Buyer service through DLD’s website or Dubai REST and provide the required information.
- Wait for eligibility confirmation: If approved, DLD sends a confirmation email containing your unique First-Time Home Buyer QR code.
- Contact participating partners: Present the QR code when approaching eligible developers or banks to access the relevant offers.
- Compare the actual terms: Review the property price, payment schedule, mortgage offer, fees, and contractual conditions before committing.
Your QR code remains valid until you purchase a property and register it with DLD. If you register but do not find a suitable home, your registration remains active, and you can continue receiving notifications about new launches.
There is no additional programme application or participation fee. Standard property registration fees and other applicable charges still need to be considered.
The Mortgage Question: How Much Deposit Will You Need?
This is where buyers need to distinguish the DLD programme from the UAE Central Bank’s mortgage regulations.
For a first home that will be occupied by the buyer and costs AED 5 million or less, the Central Bank’s maximum loan-to-value limits are:
Buyer category Maximum financing Minimum deposit based on the maximum
- UAE national – 85% 15%
- Expatriate – 80% 20%
For example, an expatriate purchasing a ready home for AED 1.5 million could potentially borrow up to AED 1.2 million, leaving a minimum property deposit of AED 300,000 under the maximum LTV limit.
This is an illustration, not a mortgage offer. The bank may approve a lower loan amount after assessing income, existing debt, credit history, and the property’s valuation. The buyer must also budget for transaction costs, insurance, valuation, and other applicable charges.
The Central Bank’s limits are not a special discount created by the Dubai programme. They are part of the wider UAE mortgage framework, and the first-home owner-occupier category has specific conditions. Off-plan purchases and investment properties should not be assumed to qualify for the same financing limits.
A Few Rules Worth Knowing Before You Apply
Some programme conditions can affect how you plan a purchase:
- Joint purchases: Both buyers must be eligible. You cannot use the programme to make a joint purchase with someone who does not qualify.
- One developer and one bank: You can approach multiple participating partners and compare offers, but programme benefits can be used with only one participating developer and one participating bank.
- Property ownership elsewhere: Owning a property outside Dubai does not automatically disqualify you.
- Buying through the programme is a one-time benefit: If you purchase a property under the initiative and later sell it, you cannot regain first-time buyer status under the programme.
These conditions make it sensible to compare your options before using the benefit. A first purchase should fit your longer-term plans, not simply take advantage of a limited offer.
Is Buying Better Than Continuing to Rent?
The programme can make buying more accessible, but the decision still comes down to your finances and how long you expect to remain in Dubai.
Renting may make more sense if your employment, location or family plans are uncertain. Buying can become more attractive when you have stable income, sufficient savings for the deposit and additional costs, and a reasonable expectation of staying in the property long enough to justify the purchase expenses.
Compare the full monthly cost of ownership with your current rent. Include mortgage payments, service charges, maintenance, insurance, and the initial transaction costs. Also consider whether the property suits your needs if you eventually decide to sell or rent it out.
How FGREALTY Can Help
FGREALTY can help first-time buyers identify suitable properties, compare participating developer options, and assess the differences between ready and off-plan homes. Buyers considering a mortgage can also use guidance on property selection and purchase requirements before approaching a participating bank for a formal assessment.
The useful starting point is not the advertised discount. It is finding a property that fits your budget, timeline, and plans for living in Dubai.
FAQs
Q: Can someone living outside the UAE apply for the programme?
A: No. Applicants must be UAE residents and at least 18 years old. Overseas buyers who do not hold UAE residency do not meet the published eligibility criteria.
Q: Can I apply if I own an apartment in Abu Dhabi?
A: Yes. DLD states that owning property in another emirate does not prevent participation, provided you do not currently own a freehold residential property in Dubai.
Q: Can I use the programme to buy a ready apartment?
A: Yes. The initiative is not limited to off-plan developments. Eligible buyers can explore ready properties through participating banks’ mortgage offers, subject to the bank’s terms.
Q: Does the programme cover the Dubai Land Department registration fee?
A: It does not automatically waive the fee. DLD provides for flexible payment arrangements through eligible credit cards, but standard registration fees remain payable unless a specific offer states otherwise.
Q: Can I apply again if I sell the home I purchased through the programme?
A: No. DLD states that purchasing a property under the programme ends your first-time buyer status, even if you later sell that property.
Q: Does programme approval mean the bank will approve my mortgage?
A: No. DLD confirms your programme eligibility and issues the QR code. The bank separately assesses your income, liabilities, credit profile, deposit, and the property before deciding whether to approve financing.